Who gets paid when accounting does more of the work itself?
Marit Wetterhus
CEO
Last week there was news from Regnskap Norge that, at first glance, looks like a deal with a software vendor, but I think it's about something much bigger. Regnskap Norge has entered into a discount agreement with Fiken, and the reasoning is interesting. According to the organization, the goal is a "more sensible distribution of the value created" between the software vendors and the accounting firms. CEO Rune Aale-Hansen puts it even more directly: the agreement should help the industry claim a "more rightful share of the value chain." I think that's an important discussion. But it also raises a question that's bigger than the relationship between Fiken and the accounting firms: who actually gets paid when the technology does more and more of the work?
There's a third party in the equation
When we talk about value creation in the accounting industry, it's easy to picture a fight between two players. On one side are the software vendors who build the technology. On the other side are the accounting firms that use it. Who pays for the systems, who captures the efficiency gains, and how much of the value creation should go to each of them? But there's a third party in this equation: the customer.
And it's only once you bring the customer into it that the discussion gets genuinely interesting. Say technology lets an accounting firm deliver in one hour a task that used to take two. Value has clearly been created. Someone got an hour back, but who owns it? If the customer is billed by the hour, the answer is fairly simple: the customer does. The firm has become twice as efficient, but bills half as many hours for the same delivery. The technology created a productivity gain, but the gain passed straight through the accounting firm and landed with the customer.
That doesn't mean hourly billing is wrong in every case. But it does mean we need to stop treating automation and profitability as the same thing. They aren't.
Cheaper technology only solves part of the problem
Regnskap Norge's agreement with Fiken is aimed in particular at small and mid-sized accounting firms that don't have the same negotiating power as the largest players. Members get access to features including reconciliation, client status, automated EHF bookkeeping, and client administration. Regnskap Norge describes the agreement as a way to give these firms better terms and a larger share of the value chain. That's good. Lower system costs and better technology can obviously improve profitability, but I think the industry needs to make sure the discussion doesn't stop there. Because even once the firm gets the technology cheaper, the same underlying question remains: what will the firm do with the time the technology frees up?
No system discount can answer that question. If two hours become one, and that last hour simply disappears from the billing, the firm has gotten a better purchasing deal on technology that reduces its own revenue. That can still make sense. But it isn't a new business model. That only happens once the freed-up capacity is used for something the customer is actually willing to pay for.
We still meet accounting firms that talk far more about reporting than about their customers' decisions
This is something I keep coming back to in conversations with accountants. We talk about reporting. Which reports the customer should get. How often they should be sent. How to produce them more efficiently.
I think that's the wrong place to start. Because the customer doesn't wake up in the morning thinking it would be lovely to get one more report. The customer wonders whether she can afford to hire. Whether the margin is good enough. Why the account keeps running dry even though the company is making money. Whether it's sound to invest. Whether sales are developing the way they should. Whether she can afford to take out a dividend. Whether the company can survive losing its biggest customer.
That's where the accountant needs to step in. The report can be part of the basis for a decision. But the report isn't the value itself. The value appears when someone understands the numbers, puts them in context, and helps the customer make better decisions. This is also where I think the value-chain discussion gets far more interesting than who gets a few more or fewer percentage points off the system cost. Because accounting firms already hold something the software vendor can't easily replace: the relationship with the customer, the history, the context, the trust.
The question is whether they actually use that position.
The greatest value might be sitting in the hour that just opened up
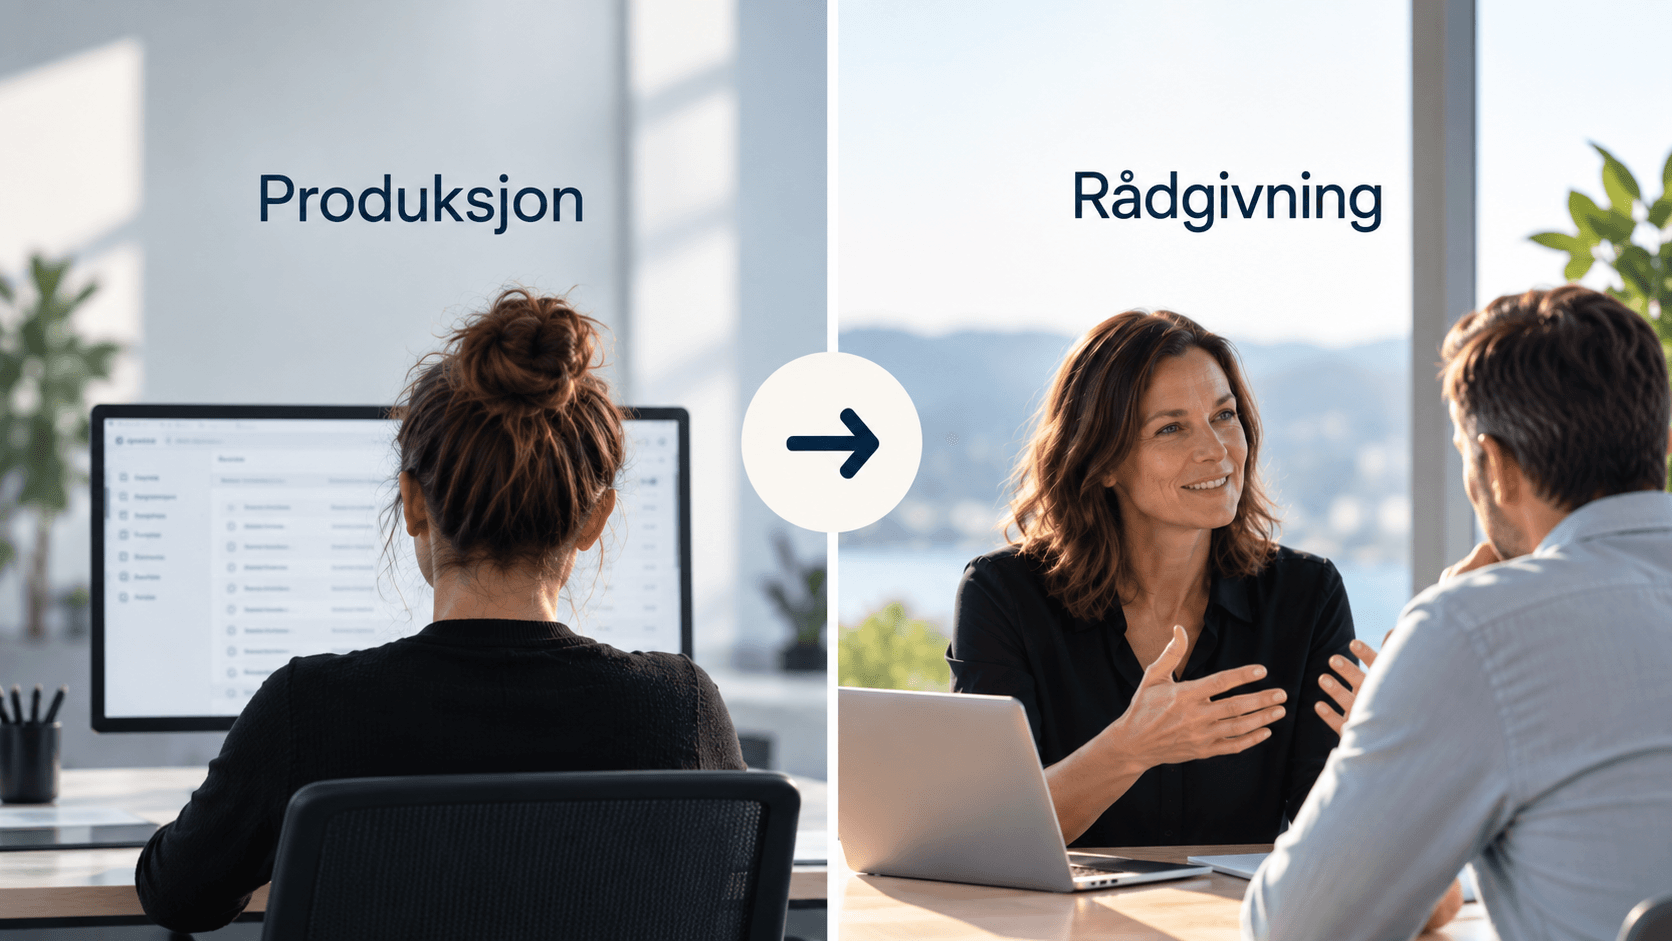
Think again about the hour technology just freed up. It can disappear. It can be used to produce more of the same for more customers. Or it can be used for something else entirely. The accountant can reach out to a customer when margins start slipping. Raise a liquidity issue before it becomes a problem. Discuss what a new hire will do to the cost base. Challenge a budget that doesn't add up. Spot customers in the portfolio who are growing fast and likely need more financial support. Now automation has done something far more interesting than cutting the cost of bookkeeping.
It has created capacity for new revenue.
And this is exactly where I think many accounting firms have a much bigger untapped opportunity than they realize. They might have 100, 300, or 1,000 customers. Inside that portfolio are businesses that are hiring, investing, financing growth, dealing with falling margins, planning liquidity, or facing hard decisions. They don't necessarily need more reports. They need someone to talk those decisions through with.
But advisory doesn't become a business model just because you call yourself an advisor
I think the industry needs to be a bit tougher on itself here. People have talked about the shift from bookkeeper to advisor for years. It's on the website. It gets discussed at conferences. It's in the strategy plans. But advisory only becomes a business model once it actually exists as a deliverable. What is the customer buying? Which customers get the offer? How often is the advisory delivered? Who does the work? What does it cost? And how much of next year's revenue is supposed to come from it? If those answers are missing, you don't have a new business model yet. You have an ambition.
That's also why I think the value-chain discussion needs to move all the way into each individual accounting firm's own budget. How much of the productivity gain from technology should become better margin? How much should become extra capacity? And how much should become new advisory revenue? Only once there's a number on that last line has someone actually decided to do something with the opportunity.
Maybe we've been arguing about the wrong value chain
That's why I think Regnskap Norge's initiative is interesting far beyond the Fiken deal itself. The organization says explicitly that the industry should claim a larger and more rightful share of the value chain. I fully agree. But I think the real opportunity lies somewhere other than in the negotiation between the software vendor and the accounting firm. It lies between the accounting firm and the customer.
Technology will keep making production cheaper. Reconciliation, bookkeeping, document handling, and more and more of reporting will require less human time. That trend is unlikely to reverse. The firm can use the freed-up time to send a lower invoice. Or it can use it to become more important to its customer.
That might be where the real fight over a "rightful share of the value chain" ends up being fought.
More posts
Shadow AI: one in three use AI outside the firm's control
Everyone reads the new AI numbers as a growth curve. We read them as a governance curve pointing the wrong way: usage has outrun approval, which makes shadow AI a standardisation problem for accounting firms – not a technology problem.
Trust Is Not a Business Model – Accounting's 2027 Choice
The Norwegian accounting profession enjoys a stable, strong reputation and rising pride among its own people. Capassa reads the new survey as unused capital with an expiry date – because clients' AI use is growing faster than firms' service catalogues.
Get new analyses in your inbox
One new post a week, never more. No product ads.
Curious about how Capassa works in practice?
Get in touch